SIPS & Eco Home Self-Build Mortgages
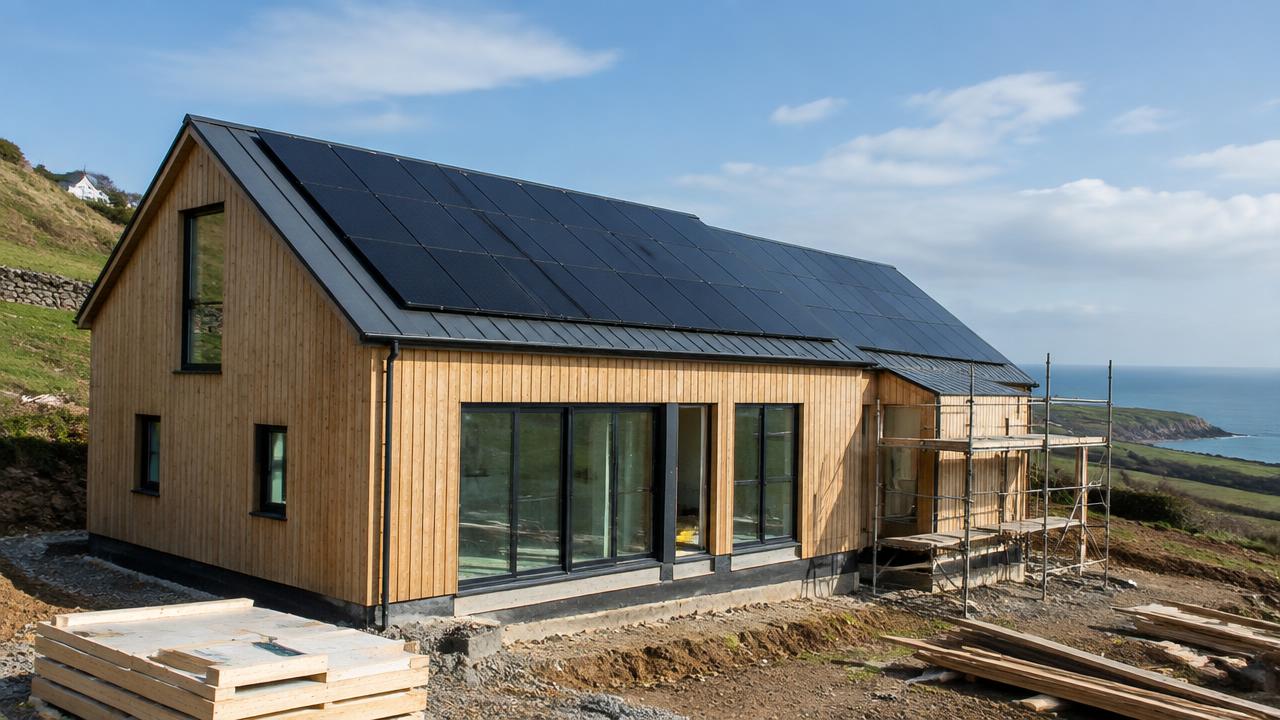
"Will a lender really back something this different?"
Ten years ago, an airtight SIPS house with solar, battery storage, a heat pump and its own water supply would have been called extreme. Today, it's what a lot of our self-build clients in Cornwall are planning.
The good news: a one-of-a-kind eco home is not a problem for the right lender. Self-build mortgages are designed for homes that don't exist yet, and many specialist lenders are comfortable with modern methods of construction.
What are modern methods of construction (MMC)?
MMC covers ways of building that differ from traditional brick and block, often made partly off-site:
- ✓SIPS (structural insulated panels): insulated panels that form the walls and roof, quick to put up and very airtight
- ✓Timber frame and cross-laminated timber (CLT)
- ✓Modular and panelised homes built in a factory and assembled on site
- ✓ICF (insulated concrete formwork)
Can you get a mortgage on a SIPS or timber frame home?
Yes. Many self-build lenders accept SIPS and other MMC builds. They'll usually want:
- ✓A recognised structural warranty (or architect's certificates) covering the build system
- ✓A manufacturer or system with a good track record, ideally with third-party accreditation
- ✓Planning permission, building regulations approval and detailed costings
Because panel systems are often paid for up front, it's worth asking about advance stage payments, so money is released before big deliveries rather than after.
Off-grid eco homes and self-build mortgages
A fully off-grid home, with solar and batteries, a borehole or rainwater system, and private drainage, can still be mortgageable. Lenders mainly want to know the home will have a reliable, year-round supply of power, heat and water, and that it would be sellable later. A clear specification and, where possible, a backup option (such as a grid connection or generator) can help.
Green mortgage rates linked to your SAP score
Your designer or energy assessor will produce a predicted SAP score and EPC rating for the finished home. Some lenders offer better rates, cashback or larger loans for homes predicted to reach a high energy rating, such as EPC A or B. A very efficient home can also mean lower running costs, which some lenders take into account when working out affordability.
Get your predicted SAP assessment done early. It can open up options before you even start building.
Why "unique" isn't a barrier
Standard mortgages compare a home with similar ones nearby. Self-build lenders instead look at your plans, costs, warranty and the expected value once finished. That's why a one-of-a-kind design is far less of an issue than people expect.
Plan your eco self-build with us
Start with our Self-Build Budget Planner, read how to get a mortgage on a plot of land, and see our self-build mortgages page. Or get in touch and we'll match your build method and energy goals with the right lender.
There are no broker fees for first-time buyers. On other cases a fee may apply, and it is always agreed with you in writing first. Your home may be repossessed if you do not keep up repayments on your mortgage.
Ready to Take the Next Step?
Book a free consultation to discuss your specific mortgage needs with our Cornwall experts.
Book Free Consultation